Choosing insurance can be confusing because the cheapest policy is not always the best policy, and the policy with the most coverage may cost more than you actually need.
Whether you’re shopping for health, auto, homeowners, renters, or life insurance, the basic question is the same: What risks could create a serious financial problem for me, and how much protection do I realistically need?
I think this is a much better starting point than simply searching for the lowest monthly premium.
The National Association of Insurance Commissioners (NAIC) recommends reviewing your coverage regularly and considering whether your current protection still matches your circumstances. Major life changes such as buying a home or car, getting married, having a child, or changing jobs can all affect your insurance needs.
Start by Identifying What You Need to Protect
Before comparing insurance companies, make a list of the things that would cause the biggest financial problems if something went wrong.
For example, you might need to protect:
- Your health and medical expenses
- Your vehicle
- Your home and personal belongings
- Your income
- Your family
- Your business
- Your savings and other assets
This step sounds basic, but it can prevent you from buying coverage simply because an agent, website, or advertisement recommended it.
Think about your actual situation.
A renter may need renters insurance but not homeowners insurance. Someone with a family that depends on their income may have a stronger reason to consider life insurance than a person with no financial dependents.
The right policy should match your risks, not someone else’s.
Understand the Main Types of Insurance
Different insurance policies protect you against different financial risks.
Health Insurance
Health insurance helps cover eligible medical expenses according to the terms of the policy.
When comparing health plans, don’t look only at the monthly premium. Consider the deductible, copays, coinsurance, out-of-pocket maximum, covered services, doctors, hospitals, and prescription coverage.
The NAIC specifically recommends considering expected healthcare needs, premiums, out-of-pocket expenses, benefits, doctors, and prescriptions when comparing health plans.
A plan with a lower premium may require you to pay more when you actually use healthcare.
Auto Insurance
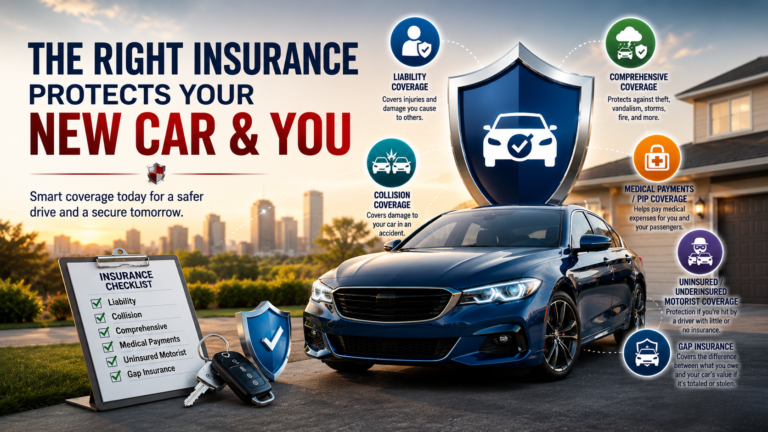
Auto insurance can protect you against several types of financial loss, including liability from an accident and damage to your vehicle depending on the coverage you purchase.
When comparing auto policies, look at liability limits, collision and comprehensive coverage, deductibles, uninsured/underinsured motorist coverage where applicable, and available discounts.
Don’t choose a policy simply because the monthly price is $20 cheaper.
A small premium difference may not be worth accepting significantly lower protection.
Homeowners Insurance
If you own a home, homeowners insurance can help protect the structure, belongings, and certain liability risks covered by the policy.
Pay close attention to exclusions.
For example, standard homeowners insurance generally does not cover flood damage, meaning separate flood insurance may be necessary when flood risk exists.
Also compare the policy’s deductible and the basis on which damaged property or the home itself would be covered.
Renters Insurance
Renters don’t need insurance for the building itself, but renters insurance can help protect personal belongings and provide liability coverage, depending on the policy.
If you rent an apartment, don’t assume your landlord’s insurance covers your personal possessions. The landlord’s policy generally protects the building, not everything you own inside it.
Life Insurance
Life insurance becomes especially important when other people depend on your income.
Instead of asking, “How much life insurance can I afford?” start with, “What financial obligations would my family have if my income disappeared?”
Consider mortgage or rent obligations, debts, childcare, education expenses, daily living costs, and the income your family may need to replace.
The NAIC provides consumer guidance on estimating appropriate life-insurance coverage and comparing policy value.
Calculate How Much Coverage You Actually Need
Once you’ve identified the type of insurance you need, determine an appropriate coverage amount.
This is where I would avoid guessing.
For homeowners insurance, for example, create an inventory of your belongings and estimate what it would take to replace important items. The NAIC recommends maintaining a home inventory because it can help determine appropriate contents coverage and assist after a loss.
For health insurance, think about your expected medical needs and how much you could realistically afford to pay out of pocket.
For auto insurance, consider the value of your vehicle, your assets, your driving situation, and the financial consequences of causing an accident.
For life insurance, consider the needs of the people who rely on your income.
The goal isn’t to insure everything for the maximum possible amount. It’s to have enough protection against losses that could seriously damage your finances.
Compare Policies, Not Just Insurance Companies
Getting quotes from several insurers is useful, but comparing the companies’ names isn’t enough.
Two policies can have similar monthly premiums but provide very different coverage.
When comparing quotes, put the important details side by side:
| What to Compare | Why It Matters |
|---|---|
| Premium | What you pay for coverage |
| Deductible | What you pay before certain benefits apply |
| Coverage limits | Maximum amount the policy may pay |
| Exclusions | Situations the policy doesn’t cover |
| Out-of-pocket costs | What you may pay when using the coverage |
| Discounts | Potential ways to reduce premiums |
| Additional coverage | Protection for risks excluded from standard coverage |
For health insurance specifically, the NAIC recommends using the Summary of Benefits and Coverage (SBC) to compare plans because it presents deductibles, copays, coinsurance, benefits, and coverage examples in a standardized format.
Don’t Automatically Choose the Cheapest Policy
This is probably the easiest mistake to make.
Suppose one auto insurance policy costs $100 per month and another costs $125. Saving $25 might sound attractive.
But if the cheaper policy has significantly lower liability limits or a higher deductible, the savings may not be worth the additional financial risk.
The same principle applies to health, homeowners, and other types of insurance.
The NAIC warns consumers to consider total costs and coverage rather than looking at premiums alone. For health insurance, for example, a lower premium can come with higher out-of-pocket costs.
Think about the cost of the insurance and the cost of being underinsured.
Check the Deductible
A deductible is the amount you generally pay out of pocket before an insurer pays for covered losses subject to the policy terms.
A higher deductible can sometimes reduce your premium, but it also means you’ll need more money available if you file a claim.
Before choosing a high deductible, ask yourself a simple question:
Could I comfortably pay this amount tomorrow if something went wrong?
If the answer is no, a slightly higher premium for a lower deductible may be more practical.
Read the Exclusions Carefully
One of the biggest surprises with insurance is discovering that something you assumed was covered actually isn’t.
Insurance policies contain exclusions, limitations, conditions, and coverage limits.
For example, the CFPB notes that standard homeowners insurance generally doesn’t cover flood damage, while certain other disaster risks may also require separate or additional coverage.
Don’t rely entirely on an advertisement or a short summary.
Read the policy documents and ask questions about anything you don’t understand.
The NAIC also recommends knowing what your policy covers, what it excludes, and what deductibles apply.
Check the Insurer Before You Buy
Price isn’t the only thing worth researching.
You should also make sure the insurer is licensed to operate in your state and investigate its reputation and financial stability.
The NAIC recommends checking whether an insurance company is licensed in your state and looking into complaints and financial strength when evaluating an insurer.
Your state insurance department can also be a useful resource. State insurance departments can help consumers understand coverage, verify licensing, and address certain insurance complaints.
Ask Questions Before Signing
If an insurance policy isn’t clear, ask.
Some useful questions include:
- What exactly does this policy cover?
- What isn’t covered?
- What is my deductible?
- What are the coverage limits?
- Are there important exclusions?
- Can my premium change?
- What discounts are available?
- What happens if I need to file a claim?
- Is additional coverage recommended for my situation?
A good insurance professional should be willing to explain the policy rather than pressure you into buying it.
The NAIC specifically advises consumers not to feel pressured and to keep asking questions until they understand the coverage.
Review Your Insurance Every Year
Buying insurance isn’t a one-time decision.
Your needs can change.
You might buy a house, purchase a new vehicle, get married, have a child, start a business, change jobs, acquire expensive belongings, or experience a significant change in income.
Those events can affect how much insurance you need.
I would make an annual insurance review part of your financial routine. Compare your current coverage with your current life rather than automatically renewing the same policy without looking at it.
The NAIC recommends reviewing insurance coverage regularly because changes in your circumstances can create a need for more—or sometimes less—coverage.
Choosing the right insurance isn’t about finding the policy with the lowest premium or the most coverage.
It’s about finding a reasonable balance between protection, cost, deductibles, coverage limits, exclusions, and your ability to handle unexpected expenses.
Start by identifying the risks that could seriously affect your finances. Then determine how much protection you need, compare several policies using the same criteria, read the exclusions, and research the insurer before making a decision.
And don’t be afraid to ask questions.
A few extra minutes spent understanding an insurance policy can be far more valuable than saving a small amount on the premium and discovering after a loss that you didn’t have the protection you thought you purchased.
Insurance is ultimately about transferring financial risk. The right policy should give you meaningful protection without forcing you to pay for coverage that doesn’t fit your actual needs.