Shopping for insurance can feel like comparing apples to oranges. One company may quote a lower premium, while another offers broader coverage. A third may have a higher deductible but better limits.
That is why I don’t think the cheapest insurance quote should automatically win.
When comparing insurance plans, the goal is to find a policy that gives you the protection you actually need at a price you can comfortably afford. The National Association of Insurance Commissioners (NAIC) recommends comparing both coverage and cost, and making sure you’re comparing similar policies rather than simply choosing the lowest price.
Here’s a practical way to compare insurance plans and rates without getting lost in the fine print.
Start by Deciding What You Need to Insure
Before requesting quotes, figure out what you actually need to protect.
Depending on your situation, that could include:
- Your health
- Your car
- Your home
- Your belongings
- Your income
- Your family
- Your business
- Your financial assets
The right coverage for one person may be completely different from another person’s needs.
For example, someone who rents an apartment doesn’t need the same property coverage as a homeowner. A person with a financed vehicle may have different auto-insurance requirements than someone driving an older car they own outright.
Starting with your needs makes it easier to reject policies that provide unnecessary coverage or leave important risks unprotected.
Get Quotes From Multiple Insurers
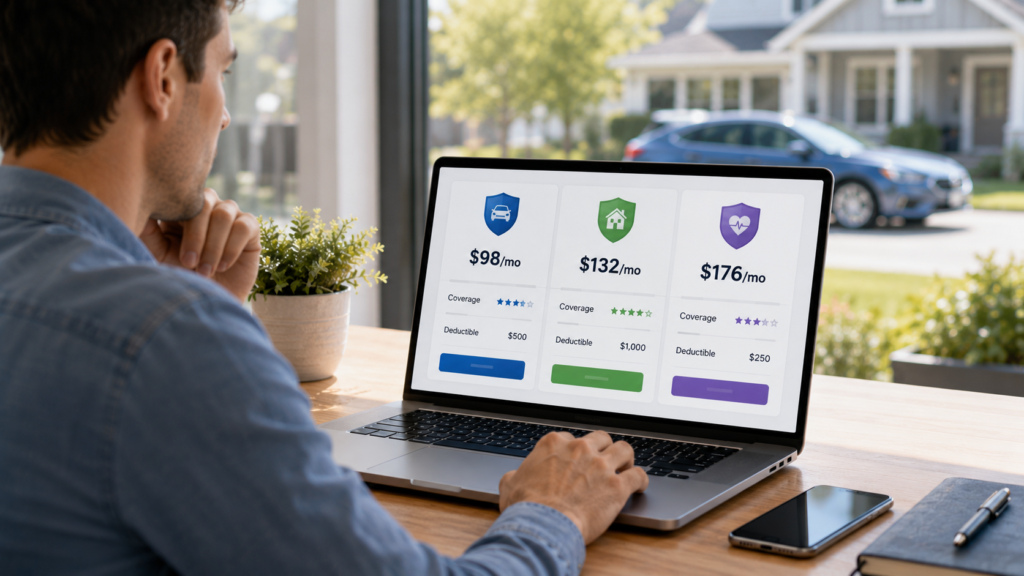
One of the simplest ways to find a competitive insurance rate is to shop around.
Don’t assume your current insurer has the lowest price simply because you’ve been with the company for years.
The NAIC notes that different insurance companies can charge different rates for similar coverage. It also recommends considering factors beyond price, including claims service and the insurer’s financial condition.
I’d try to get at least three comparable quotes when possible.
You can obtain quotes directly from insurers, through agents, or through independent agents who may represent multiple companies.
The important part is making sure you’re actually comparing equivalent coverage.
Compare the Same Coverage Limits
This is where many insurance comparisons go wrong.
Imagine Company A quotes $110 per month and Company B quotes $135.
At first glance, Company A looks like the obvious winner.
But what if Company A has lower liability limits, a higher deductible, or fewer included protections?
You aren’t really comparing prices anymore. You’re comparing different products.
The NAIC’s auto-insurance shopping guidance specifically recommends comparing the same coverage and deductibles when reviewing quotes.
When requesting quotes, try to keep these details consistent:
- Coverage limits
- Deductibles
- Optional coverage
- Policy type
- Drivers or household members
- Property details
- Vehicle information
- Relevant discounts
Once everything is comparable, the price difference becomes much more meaningful.
Look Beyond the Monthly Premium
The premium is the amount you pay to keep the insurance policy active, but it isn’t necessarily the amount you’ll pay when something goes wrong.
For example, a health plan might have a low monthly premium but a relatively high deductible and higher out-of-pocket costs when you need care.
The NAIC points out that lower-premium health plans can come with higher deductibles and other out-of-pocket costs.
The same basic idea applies to other types of insurance.
When comparing policies, look at:
Premium: What you pay for the policy.
Deductible: What you generally pay out of pocket before the insurer pays its share for covered losses or services.
Coverage limits: The maximum amount the policy may pay for a covered loss.
Out-of-pocket costs: What you may have to pay when you use the insurance.
Exclusions: Situations or losses the policy doesn’t cover.
The cheapest premium isn’t necessarily the cheapest policy once you consider the entire financial picture.
Understand the Deductible
The deductible deserves special attention because changing it can significantly affect your premium.
Generally, choosing a higher deductible can reduce the premium, while a lower deductible can increase the premium.
The NAIC gives the same general guidance for auto and homeowners insurance: higher deductibles can reduce premiums, but you need to be able to afford the deductible if you have a claim.
For example, imagine you’re comparing two auto policies:
- Policy A: $500 deductible
- Policy B: $1,000 deductible
If Policy B saves you $30 per month, that’s $360 per year.
But if you have a covered accident, you may have to pay an additional $500 out of pocket compared with the lower-deductible policy.
That’s why I wouldn’t raise a deductible just to get a lower monthly price unless I had enough savings to handle the larger expense.
Check Coverage Limits Carefully
Coverage limits determine how much protection a policy provides for covered losses.
This is especially important with auto and homeowners insurance because a serious accident or property loss can create expenses far greater than your annual premium.
For auto insurance, compare liability limits and other applicable coverages. For homeowners insurance, look at dwelling, personal-property, liability, and other relevant limits.
Don’t automatically choose the minimum available coverage simply because it produces the lowest quote.
Your assets, financial situation, property, and personal risk should influence the amount of protection you carry.
Pay Attention to Exclusions
Insurance doesn’t cover everything.
Every policy has limitations and exclusions, and these can be just as important as the benefits listed in the policy.
For example, standard homeowners insurance generally doesn’t cover flood damage, so someone exposed to flood risk may need separate coverage.
When comparing policies, ask:
“What isn’t covered?”
That question can reveal differences that aren’t obvious from the premium or headline coverage.
If an insurer excludes something important to you, find out whether additional coverage or an endorsement is available.
Compare Health Insurance Differently
Health insurance requires a little more detailed comparison because the cost isn’t limited to the monthly premium.
When evaluating a health plan, look at:
- Monthly premium
- Deductible
- Copays
- Coinsurance
- Out-of-pocket maximum
- Provider network
- Prescription coverage
- Covered services
The NAIC recommends estimating your expected healthcare costs and comparing premiums, out-of-pocket expenses, and benefits across plans.
If you’re comparing Marketplace or employer-sponsored health plans, the Summary of Benefits and Coverage (SBC) can be especially useful because plans present important cost-sharing information in a standardized format.
I would pay particular attention to whether your preferred doctors, hospitals, and medications are covered. A plan that looks inexpensive on paper may be less useful if it doesn’t work well with your healthcare needs.
Look for Available Discounts
Once you’ve found policies with appropriate coverage, check for discounts.
Depending on the type of insurance and insurer, discounts may be available for things such as:
- Bundling policies
- Multiple vehicles
- Safety features
- Defensive-driving courses
- Claims-free history
- Security devices
- Certain memberships or affiliations
The exact discounts vary by company and state.
For auto insurance, the NAIC notes that insurers may offer discounts related to multiple vehicles, safety equipment, defensive-driving courses, and bundling.
Ask the insurer to review all discounts you may qualify for rather than assuming the online quote includes everything.
Check the Insurance Company’s Reputation
A low premium doesn’t help much if you’re unhappy with the company’s claims service when you actually need to use your policy.
Before buying, research the insurer’s reputation, financial strength, and complaint information.
The NAIC recommends checking that an insurer or agent is properly licensed in your state and considering financial strength and complaint information when evaluating an insurance company.
Your state insurance department can also be a useful source of consumer information.
Don’t Let an Agent Pressure You
A good insurance agent should help you understand your options rather than make you feel rushed.
If someone tells you that you need to buy a policy immediately, don’t understand why you’re being charged a particular fee, or refuses to explain important exclusions, take a step back.
Ask for the policy documents and compare the offer with other insurers.
You are allowed to take time to understand what you’re buying.
Review Your Insurance Every Year
Insurance isn’t something you should buy once and forget about.
Your needs can change.
You might buy a new car, move to another home, get married, have a child, start a business, acquire valuable belongings, or experience changes in your income.
Those changes can affect the amount and type of coverage you need.
The NAIC recommends reviewing insurance coverage regularly and checking whether your current protection still matches your circumstances.
I would make an annual insurance review part of your financial routine.
Even if you don’t switch insurers, reviewing your coverage can help you identify outdated limits, unnecessary coverage, missed discounts, or new risks.
A Simple Way to Compare Insurance Quotes
If you’re comparing several policies, create a simple table or spreadsheet.
For each insurer, record:
| Factor | Company A | Company B | Company C |
|---|---|---|---|
| Annual premium | — | — | — |
| Deductible | — | — | — |
| Coverage limits | — | — | — |
| Major exclusions | — | — | — |
| Optional coverage | — | — | — |
| Discounts | — | — | — |
| Claims/service information | — | — | — |
This makes it much easier to see whether the cheapest quote is actually the best overall value.
The best way to compare insurance plans and rates is to compare like with like.
Get multiple quotes, use the same coverage limits and deductibles when possible, examine exclusions, consider out-of-pocket costs, check available discounts, and research the insurer itself.
Most importantly, don’t make your decision based solely on the monthly premium.
Insurance exists to protect you from potentially large financial losses. The goal isn’t necessarily to find the cheapest policy. It’s to find a policy that provides meaningful protection at a price that fits your budget.
A little comparison work before buying can help you avoid paying for coverage you don’t need—or discovering too late that the inexpensive policy didn’t provide the protection you expected.