If you’re paying off a car loan and your credit score improves, you may wonder whether your monthly payment or interest rate will automatically go down. The short answer is usually no. An improved credit score does not automatically change the terms of an existing auto loan.
However, a higher credit score can make a significant difference when you refinance the loan or apply for another auto loan in the future. A stronger credit profile may help you qualify for a lower interest rate, which can reduce the amount of interest you pay over the life of the loan.
Understanding how credit scores and auto-loan rates work can help you decide whether refinancing makes sense.
Does a Higher Credit Score Automatically Lower Your Car Payment?
Generally, no.
When you sign an auto loan agreement, the interest rate and payment are normally established according to the terms of that contract. If your credit score increases six months later, the lender typically doesn’t automatically recalculate your interest rate.
For example, suppose you financed a vehicle at a 10% APR when your credit score was relatively low. A year later, your credit score improves substantially.
Your existing loan will generally continue using the agreed-upon 10% APR unless you refinance or otherwise modify the loan.
That’s an important distinction:
Improving your credit can help you qualify for better financing, but it doesn’t automatically rewrite an existing loan contract.
Why Does Credit Score Matter for Car Loans?
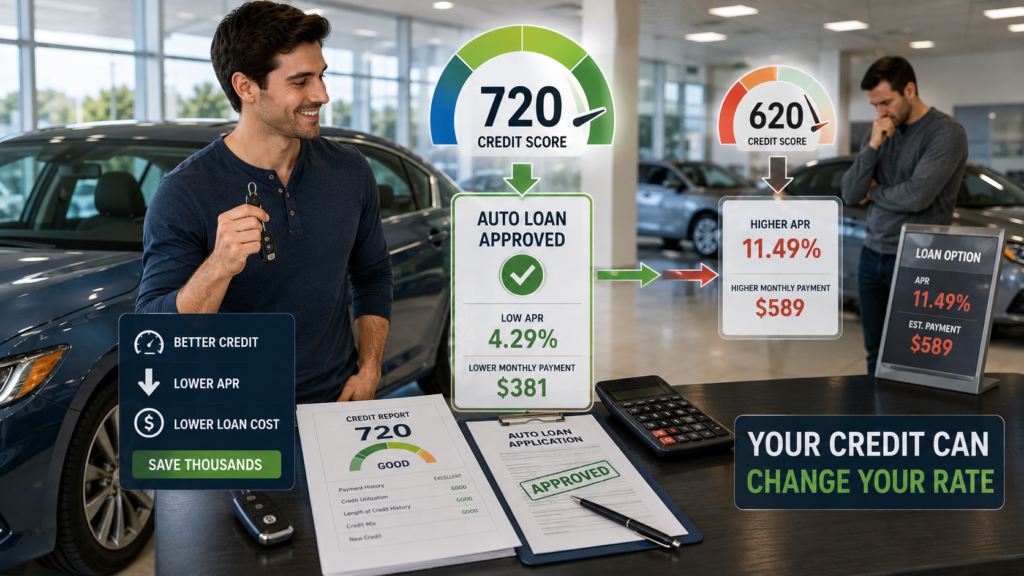
Lenders use credit information as one factor in assessing the risk of lending money.
A borrower with a strong credit history may generally be viewed as less likely to default than someone with a history of missed payments or significant credit problems.
Because of that difference in risk, lenders may offer different interest rates to borrowers with different credit profiles.
For example, two people could purchase similar vehicles and borrow similar amounts but receive different APRs because their credit histories and other financial factors are different.
Your credit score isn’t the only factor involved. Lenders may also consider:
- Income
- Employment
- Existing debts
- Loan amount
- Down payment
- Vehicle type
- Loan term
- Credit history
- Previous auto-loan repayment history
Can a Better Credit Score Help You Refinance a Car Loan?
Potentially, yes.
Refinancing means replacing your existing auto loan with a new loan, usually with a different lender or different terms.
If your credit has improved since you originally financed the vehicle, you may qualify for a more competitive interest rate than you received when you first borrowed the money.
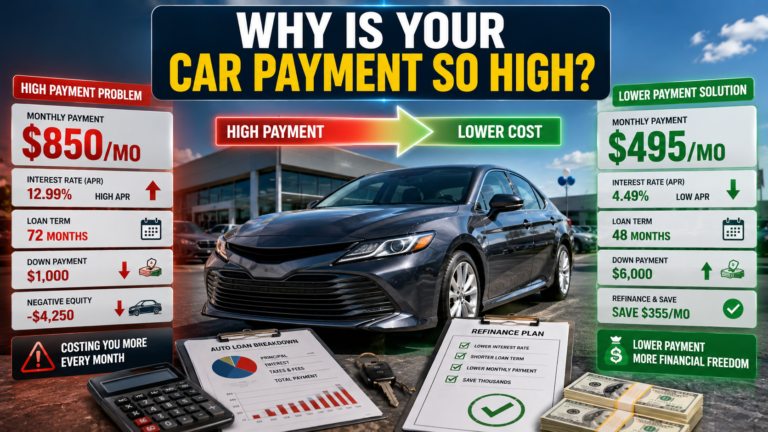
For example, imagine you originally borrowed $30,000 at a 10% APR because your credit profile was weaker.
After making consistent payments and improving your credit, you may qualify for a lower rate when applying for refinancing.
If the new loan has a significantly lower APR and reasonable fees, refinancing could reduce your interest cost.
However, refinancing isn’t automatically beneficial. You need to compare the complete cost of the new loan with what remains on your current loan.
How Much Can a Higher Credit Score Save You?
The potential savings depend on how much you owe, your current interest rate, the new interest rate, and how long remains on your loan.
Consider a simplified example.
Suppose you have:
- $25,000 remaining
- 9% current APR
- 48 months remaining
If you refinance at a substantially lower rate, your interest cost could decrease.
But the savings aren’t determined by your credit score alone. The lender’s offer, remaining balance, loan term, fees, and vehicle value all matter.
This is why it’s better to compare actual refinancing offers rather than assuming a certain credit score will guarantee a specific rate.
How Long Does It Take for a Credit Score to Improve?
There’s no fixed timeline.
Credit scores can change as lenders report updated information to the credit bureaus. The timing depends on when creditors report and what changes occur in your credit history.
Some factors that can help your credit profile over time include:
- Paying bills on time
- Reducing revolving credit balances
- Avoiding unnecessary new debt
- Keeping accounts in good standing
- Correcting inaccurate information on credit reports
If your score improved because you consistently paid your existing auto loan on time, that’s particularly useful because it demonstrates responsible repayment behavior.
However, don’t take on unnecessary debt just to increase your credit score.
Should You Refinance as Soon as Your Credit Score Improves?
Not necessarily.
A higher credit score may make refinancing more attractive, but you should look at the entire financial picture.
Before refinancing, consider:
Your current APR:
If your existing rate is already competitive, refinancing may produce little benefit.
Remaining balance:
The less you owe, the smaller the potential interest savings may be.
Remaining loan term:
Refinancing near the end of a loan may not make sense if there isn’t enough time left to recover refinancing costs.
Fees:
Check whether the new loan has application fees, title fees, or other costs.
Vehicle value:
Some lenders have restrictions based on the vehicle’s age, mileage, or value.
New loan term:
A lower monthly payment isn’t necessarily a lower total cost if the new loan extends your repayment period substantially.
Lower Monthly Payment Doesn’t Always Mean a Cheaper Loan
This is one of the most important things to understand when refinancing.
Suppose you have three years left on your current loan. A new lender offers a lower interest rate but extends the repayment period to five years.
Your monthly payment could fall.
But because you’re making payments for an additional two years, you could potentially pay more interest overall.
Always compare the total remaining cost of your current loan with the total cost of the proposed refinance.
Don’t make your decision based solely on the monthly payment.
What Credit Score Is Considered Good for a Car Loan?
There isn’t one universal credit score that guarantees a low auto-loan rate.
Lenders use their own underwriting standards, and different credit-scoring models may produce different scores.
In general, stronger credit profiles tend to give borrowers access to more competitive financing options.
But even if your credit score isn’t excellent, improving it can still help over time.
For example, moving from a weaker credit profile to a stronger one could expand your options when you’re ready to refinance or purchase another vehicle.
What Else Can Lower the Cost of a Car Loan?
Credit improvement is only one part of the equation.
You can potentially reduce borrowing costs by:
Making a Larger Down Payment
A larger down payment means borrowing less money.
Choosing a Shorter Loan Term
Shorter loans often have higher monthly payments but can reduce total interest.
Comparing Multiple Lenders
Different lenders may offer different rates to the same borrower.
Improving Your Debt-to-Income Position
Reducing existing debt can strengthen your overall financial profile.
Shopping for a Vehicle Within Your Budget
Borrowing less can sometimes make a bigger difference than negotiating a small reduction in APR.
What If Your Credit Score Goes Down?
The opposite situation is also worth understanding.
If your credit score decreases after you take out a fixed-rate auto loan, your existing interest rate generally doesn’t automatically increase.
This is another reason to understand that credit score and loan APR aren’t continuously linked after a fixed-rate loan is established.
Your credit score primarily matters when you’re applying for new credit or refinancing.
Can You Ask Your Current Lender for a Lower Rate?
You can ask.
However, an improved credit score doesn’t necessarily mean your current lender will modify your existing loan.
Some lenders may offer options in certain circumstances, while others may require you to refinance through a new loan.
If you’re interested in lowering your rate, compare your current loan with available refinancing offers.
Make sure you understand whether there are any costs involved before making a decision.
When Does Refinancing Make the Most Sense?
Refinancing may be worth considering when several things line up.
For example:
- Your credit score has improved
- Your current APR is relatively high
- You have made consistent payments
- You still have a meaningful balance remaining
- You can qualify for a significantly lower rate
- Refinancing fees are low
- Your vehicle meets the lender’s requirements
- The new loan doesn’t unnecessarily extend your repayment period
The larger the difference between your current rate and the new rate, the more potential there may be for savings.
But always calculate the numbers before signing.
How to Decide if Refinancing Is Worth It
Start by finding out exactly how much you still owe and how many payments remain.
Then compare that information with the proposed refinance.
Look at:
- Current remaining balance
- Current APR
- Current monthly payment
- Remaining loan term
- New APR
- New monthly payment
- New loan term
- Refinancing fees
- Total interest under each option
This comparison gives you a much clearer picture than simply looking at your new interest rate.
A higher credit score does not automatically make an existing car loan cheaper. If you have a fixed-rate auto loan, your agreed-upon interest rate and payment generally remain unchanged even if your credit score improves.
Where a stronger credit score can make a difference is when you apply for new financing or refinance your existing loan. A better credit profile may help you qualify for a lower APR, potentially reducing your interest costs.
Before refinancing, don’t focus only on your credit score or monthly payment. Compare the new APR, remaining balance, loan term, fees, and total repayment cost with your existing loan.
If your credit has improved substantially and your current auto-loan rate is relatively high, checking your refinancing options could be worthwhile. Just make sure the numbers actually work in your favor before replacing your existing loan.