Starting to invest can feel overwhelming, especially when you’re not sure how much money you should put into the market each month. Some beginners believe they need hundreds or thousands of dollars to get started, while others worry that investing a small amount isn’t worth it.
The reality is simpler: there is no single monthly investment amount that works for everyone. The right amount depends on your income, expenses, emergency savings, debt, financial goals, and how long you plan to invest.
For many beginners, the most important step isn’t finding a perfect number. It’s developing a consistent investing habit that can grow as their income increases.
How Much Should a Beginner Invest Each Month?
A reasonable starting point for many people is to invest 5% to 10% of their monthly take-home income.
For example:
| Monthly Take-Home Income | 5% Investment | 10% Investment |
|---|---|---|
| $2,500 | $125 | $250 |
| $3,000 | $150 | $300 |
| $4,000 | $200 | $400 |
| $5,000 | $250 | $500 |
| $6,000 | $300 | $600 |
These aren’t rules or guarantees. Someone with high expenses may need to start with less, while someone with low expenses and strong savings may be able to invest more.
The key is choosing an amount you can maintain consistently without creating financial stress.
Is $100 a Month Enough to Start Investing?
Yes.
You don’t need a large amount of money to begin building an investment portfolio.
Investing $100 every month may seem insignificant compared with someone investing $1,000 monthly, but consistent contributions can add up over many years.
For example, investing $100 per month means contributing:
- $1,200 per year
- $6,000 over five years
- $12,000 over ten years
- $24,000 over twenty years
Those figures don’t include investment returns.
If your investments grow over time, your account balance could become larger than your total contributions because of compound growth. However, investment returns aren’t guaranteed, and markets can decline.
The important lesson is that starting early can give your money more time to potentially grow.
Should You Invest Before Building an Emergency Fund?
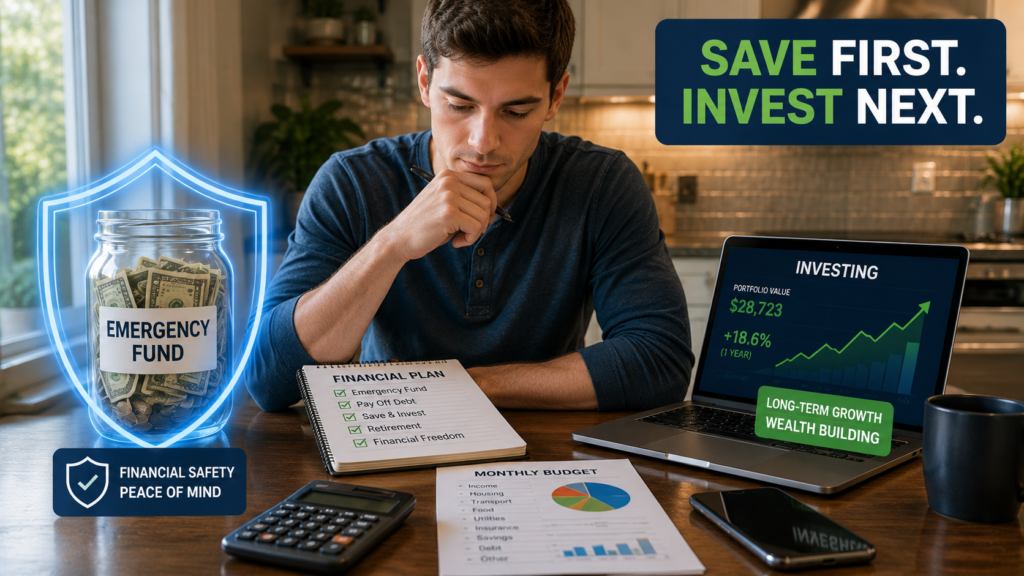
Usually, beginners should think about financial stability before putting large amounts of money into investments.
An emergency fund is designed to cover unexpected expenses such as:
- Car repairs
- Medical bills
- Temporary loss of income
- Home repairs
- Unexpected family expenses
Without emergency savings, you may be forced to sell investments during a market downturn to pay for an emergency.
A common goal is to eventually build enough savings to cover several months of essential expenses. The appropriate amount depends on your job stability, household situation, income, and monthly obligations.
You don’t necessarily have to wait until your emergency fund is completely built before investing anything. Some people choose to invest a small amount while simultaneously building their savings.
Pay Attention to High-Interest Debt
Another important consideration is debt.
If you have high-interest credit card debt, aggressively investing while carrying that debt may not be the most efficient use of your money.
For example, if a credit card is charging a very high interest rate, paying down that balance provides a more predictable financial benefit than hoping an investment will produce a higher return.
This doesn’t mean you can never invest while paying off debt.
Instead, consider balancing your priorities:
Emergency savings → high-interest debt → retirement and long-term investing
The exact order can vary depending on your financial circumstances.
Take Advantage of Employer Retirement Plans
If your employer offers a retirement plan such as a 401(k), check whether the company provides an employer match.
An employer match can be an important part of your overall compensation.
For example, if your employer matches a portion of your contributions, contributing enough to receive the full available match may be worth considering, assuming the plan’s terms and your financial situation make sense.
After that, you can decide whether additional investing should go toward your workplace retirement account, an IRA, or a taxable brokerage account.
How Much Should You Invest for Retirement?
Retirement investing is one of the most common reasons people invest every month.
A frequently used long-term target is around 10% to 15% of income, including employer contributions in some financial planning approaches. But this isn’t a universal requirement.
Your ideal percentage depends on factors such as:
- Your current age
- Desired retirement age
- Current retirement savings
- Income
- Expected lifestyle
- Employer contributions
- Other sources of retirement income
- Investment returns
Someone starting at age 25 may have a different target from someone beginning at age 45.
If you’re just starting, don’t become discouraged because you can’t immediately invest 15% of your income.
Starting with 3%, 5%, or 10% and gradually increasing your contribution can be more realistic.
What If You Can Only Invest $50 a Month?
That’s okay.
Investing $50 per month is better than waiting indefinitely for the “perfect” financial situation if your essential expenses are covered and you’re not neglecting more urgent financial priorities.
The goal at the beginning is often to establish the habit.
You could start with $50 per month and increase your contribution when:
- You receive a raise
- Your debt decreases
- Your rent or other expenses fall
- You receive a bonus
- Your emergency fund reaches a comfortable level
Small increases can make a meaningful difference over a long investing period.
What Percentage of Your Income Should You Invest?
A percentage-based approach can make investing easier because the amount automatically adjusts as your income changes.
For example, you might begin with:
5% of take-home income
After several months, if your budget remains comfortable, you could increase it to:
7% → 10% → 12% → 15%
You don’t need to make a huge jump all at once.
Another useful strategy is increasing your investment contribution whenever you receive a salary increase.
If you receive a 5% raise, you might direct part of that increase toward investing rather than increasing your lifestyle expenses by the full amount.
Should Beginners Invest Every Month?
For most long-term investors, consistency is more important than trying to predict the best day to invest.
A strategy known as dollar-cost averaging involves investing a set amount at regular intervals regardless of whether the market is rising or falling.
For example, you could invest $200 on the same date every month.
When prices are higher, your money buys fewer shares. When prices are lower, the same contribution buys more shares.
This doesn’t eliminate investment risk or guarantee profits, but it can provide a disciplined approach and reduce the temptation to constantly guess when the market will rise or fall.
Where Should a Beginner Invest?
The appropriate investment depends on your goals, timeline, and risk tolerance.
Long-term investors commonly consider diversified investments such as:
- Broad-market index funds
- Mutual funds
- Exchange-traded funds
- Retirement accounts
- Target-date funds
Diversification means spreading your money across different investments rather than relying heavily on one company or asset.
Beginners should also understand that investing involves risk. Stocks can lose value, sometimes significantly, and past performance doesn’t guarantee future results.
Money needed in the near future generally shouldn’t be exposed to the same level of market risk as money intended for a long-term goal.
How Much Should You Invest Based on Your Income?
Here’s a simple example.
Suppose your monthly take-home income is $4,000.
If you invest 5%, that would be:
$200 per month
At 10%:
$400 per month
At 15%:
$600 per month
If $600 would make it difficult to pay essential bills or maintain emergency savings, investing $200 may be more appropriate.
Financial progress isn’t about choosing the largest possible contribution. It’s about choosing a sustainable contribution and increasing it when your financial situation improves.
Common Investing Mistakes Beginners Should Avoid
Starting to invest is important, but avoiding major mistakes is equally valuable.
Investing Money You Need Soon
Don’t invest money you expect to need for an upcoming expense if a market decline could cause a serious financial problem.
Chasing Quick Profits
Investing isn’t a guaranteed way to get rich quickly. Be skeptical of anyone promising easy or guaranteed returns.
Putting Everything Into One Investment
Concentration can increase risk. Diversification can help reduce the impact of one investment performing poorly.
Checking Your Portfolio Constantly
Long-term investing generally requires patience. Constantly reacting to daily market movements can encourage emotional decisions.
Increasing Your Lifestyle Too Quickly
As your income rises, consider increasing your investment contributions before allowing all of the extra money to disappear into higher spending.
A Simple Monthly Investing Plan for Beginners
If you’re unsure where to start, consider a simple framework.
Step 1: Calculate your monthly take-home income.
Step 2: List essential expenses and minimum debt payments.
Step 3: Build an emergency savings cushion.
Step 4: Address high-interest debt.
Step 5: Check whether your employer offers retirement contributions or matching.
Step 6: Start investing a manageable percentage, such as 5%.
Step 7: Automate the contribution if possible.
Step 8: Increase your investment percentage as your financial situation improves.
This approach doesn’t require you to perfectly predict the market.
A beginner doesn’t need to invest a huge amount every month to get started. For many people, investing 5% to 10% of take-home income can be a reasonable starting point, while others may need to begin with $50 or $100 per month.
Your first priority should be creating a financial foundation that includes manageable expenses, emergency savings, and a plan for high-interest debt. From there, consistent investing can become part of your monthly budget.
The most important thing is to start with an amount you can maintain and increase it gradually over time.
Investing is a long-term process, not a race. The amount you invest today matters, but so do consistency, time, diversification, and keeping your investment strategy aligned with your financial goals.