If you’re filling out the FAFSA or reviewing a college financial aid offer, you may see two terms that look almost identical: Direct Subsidized Loan and Direct Unsubsidized Loan.
The difference can seem confusing at first, but there is one key point to remember:
A subsidized loan can have the federal government cover the interest during certain periods, while interest on an unsubsidized loan starts accumulating from the time the loan is first disbursed.
That difference can affect how much you eventually have to repay.
Both are federal student loans offered by the U.S. Department of Education, but they have different eligibility rules and interest treatment.
What Is a Subsidized Loan?
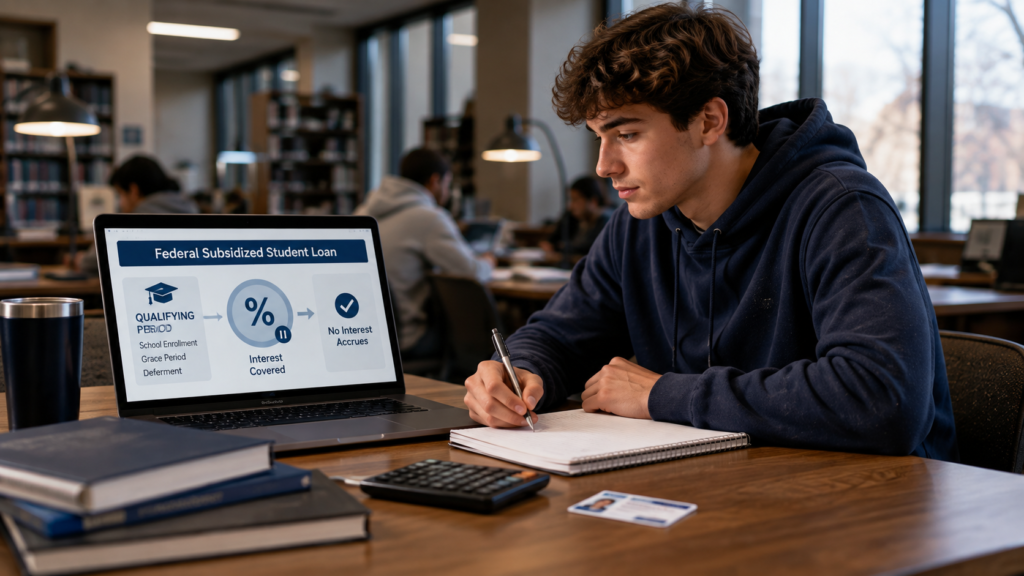
A Direct Subsidized Loan is a federal student loan available to eligible undergraduate students who demonstrate financial need.
The biggest advantage is the way interest is handled.
While you’re enrolled in school at least half-time, you generally aren’t charged interest on a Direct Subsidized Loan. The federal government also generally covers the interest during the six-month grace period after you leave school and during qualifying deferment periods.
That can make subsidized loans less expensive than comparable unsubsidized borrowing.
For example, imagine you borrow $5,000 in a subsidized loan and don’t make payments while you’re in school. If you qualify for the interest benefit during that period, your balance doesn’t grow from interest during those covered periods.
Of course, you still have to repay the original principal and any interest that becomes your responsibility later.
What Is an Unsubsidized Loan?
A Direct Unsubsidized Loan is also a federal student loan, but financial need is not required for eligibility.
The major difference is that interest begins accumulating from the date the loan is first disbursed. This happens even while you’re enrolled in school.
You’re responsible for that interest.
You can choose to pay the interest while you’re in school, or it may accumulate and potentially be added to the principal under applicable circumstances.
For example, suppose you borrow $5,000 in an unsubsidized loan. Even though you’re still attending college and aren’t required to make regular payments yet, interest can continue accumulating.
That’s why an unsubsidized loan can ultimately cost more than the original amount borrowed.
Subsidized vs. Unsubsidized Loans: The Main Difference
The easiest way to remember the difference is who is responsible for the interest during certain periods.
| Feature | Direct Subsidized Loan | Direct Unsubsidized Loan |
|---|---|---|
| Available to | Eligible undergraduate students | Eligible undergraduate, graduate and professional students |
| Financial need required? | Yes | No |
| Interest while in school | Generally not charged | Accumulates |
| Interest during six-month grace period | Generally not charged | Accumulates |
| Who is responsible for interest? | Government covers interest during qualifying periods | Borrower is responsible |
| FAFSA required? | Yes | Yes |
| Six-month grace period | Generally yes | Generally yes |
Federal Student Aid confirms that both loan types require at least half-time enrollment for eligibility and generally provide a six-month grace period before repayment begins.
Why Does the Interest Difference Matter?
Interest is what makes borrowing more expensive than simply receiving money upfront.
Federal Direct Loans accrue interest daily based on the outstanding principal balance and applicable interest rate.
With an unsubsidized loan, interest can build while you’re in college.
That means two students could borrow similar amounts but eventually owe different amounts depending on the type of loan and how much interest accumulates.
This is one reason I wouldn’t look at the amount offered by a school and assume the loans are essentially the same.
A $5,000 subsidized loan and a $5,000 unsubsidized loan may look identical on a financial aid letter, but their interest treatment can be very different.
Which Loan Should You Choose First?
If you’re eligible for both types and you need to borrow money, Direct Subsidized Loans generally make more sense to accept first because of the interest benefit during qualifying periods.
Federal Student Aid gives the same general recommendation: accept a Direct Subsidized Loan first and then consider an unsubsidized loan if you still need additional financial aid.
However, that doesn’t mean you should automatically accept the entire amount offered.
You can generally decline a loan or request a lower amount if you don’t need all the money.
Borrowing less means having less to repay later.
What Happens to Unsubsidized Loan Interest While You’re in School?
This is where many first-time borrowers get caught off guard.
Imagine you receive an unsubsidized loan and don’t make any interest payments while attending school.
The interest doesn’t simply disappear.
It continues accumulating according to the loan’s terms. If unpaid interest is capitalized under applicable circumstances, the interest can be added to the principal balance, meaning future interest may be calculated on a larger balance.
That’s why making voluntary interest payments while you’re in school can sometimes reduce the amount you ultimately repay.
Even small payments can help if you have the financial ability to make them.
Do Both Loans Have a Grace Period?
Generally, yes.
Direct Subsidized and Direct Unsubsidized Loans generally have a six-month grace period after you graduate, leave school, or drop below half-time enrollment before regular repayment begins.
But the grace period doesn’t mean interest works the same way on both loans.
For a subsidized loan, the federal government generally covers the interest during the qualifying grace period.
For an unsubsidized loan, interest continues to accumulate.
That distinction is easy to overlook when you’re focused on finishing school.
Who Qualifies for Subsidized Loans?
Eligibility for Direct Subsidized Loans is generally limited to undergraduate students who demonstrate financial need.
Your school determines your eligibility and the amount you may receive based on factors such as your financial need, cost of attendance, and other financial aid.
Because subsidized loans are need-based, not every student will qualify.
If you don’t qualify for a subsidized loan, you may still be eligible for a Direct Unsubsidized Loan.
Are Unsubsidized Loans Bad?
Not necessarily.
An unsubsidized loan isn’t automatically a bad financial decision. It can provide valuable funding when scholarships, grants, savings, and other resources aren’t enough to cover education costs.
The important thing is understanding the cost.
Before accepting an unsubsidized loan, look at how much you’re borrowing, the interest rate, expected repayment period, and how much interest could accumulate.
Federal Student Aid also recommends borrowing only what you need rather than automatically accepting the maximum amount offered.
A Simple Example
Imagine two students each borrow $4,000 for school.
Student A receives a subsidized loan.
During qualifying periods while the student is enrolled at least half-time and during the grace period, the federal government generally covers the interest.
Student B receives an unsubsidized loan.
Interest begins accumulating from the first disbursement, even though the student is still in school.
Both students borrowed $4,000, but the eventual cost can differ because of the way interest is handled.
The exact amount of interest will depend on the applicable interest rate, timing of disbursements, outstanding balance, and payments.
What Should You Consider Before Accepting Either Loan?
Don’t look only at the amount you’re being offered.
I’d check these things first:
- How much do I actually need to borrow?
- Am I eligible for subsidized loans?
- What interest rate applies?
- How much could interest add to my balance?
- Can I pay some interest while I’m in school?
- What will my estimated monthly payment be after graduation?
- Are there grants or scholarships I can use instead?
- Can I reduce the amount I’m borrowing?
Remember that grants and scholarships generally don’t have to be repaid, unlike loans, although specific circumstances can result in aid being repaid.
The difference between subsidized and unsubsidized loans mostly comes down to interest.
With a Direct Subsidized Loan, the federal government generally covers interest during certain qualifying periods, including while you’re enrolled at least half-time and during the six-month grace period.
With a Direct Unsubsidized Loan, interest begins accumulating from the first disbursement, and you’re responsible for that interest.
If you’re eligible for both and need to borrow, a sensible approach is usually to consider the subsidized loan first and use an unsubsidized loan only for the additional amount you actually need.
Most importantly, don’t treat the amount shown on your financial aid offer as money you have to take. A loan is still debt. The less you borrow today, the less you’ll have to repay after college.