Yes, it is possible to have two insurance policies covering the same person, property, or risk. However, having two policies does not usually mean you can collect twice for the same covered loss.
This situation is often called double insurance or overlapping insurance, and the rules can vary depending on the type of insurance, the policy language, and the circumstances of the claim.
For example, you might accidentally have two auto insurance policies covering the same vehicle, two homeowners policies covering the same property, or multiple health insurance plans. In other situations, having more than one policy may be intentional, such as having a primary health plan along with secondary coverage.
The important question isn’t simply whether you can have two policies. It’s whether having both policies makes financial sense and how the insurers will coordinate if you make a claim.
What Happens If Two Policies Cover the Same Loss?
Insurance is generally designed to compensate you for a covered financial loss rather than allow you to make a profit from that loss.
Suppose your home suffers $20,000 in covered damage and you have two applicable property insurance policies.
You generally can’t expect to receive $20,000 from each insurer and walk away with $40,000.
Instead, the policies may contain provisions explaining how the insurers will share responsibility for the covered loss.
The exact process depends on the policies and applicable state law, so you should never assume that simply having multiple policies guarantees multiple payouts.
Why Would Someone Have Two Insurance Policies?
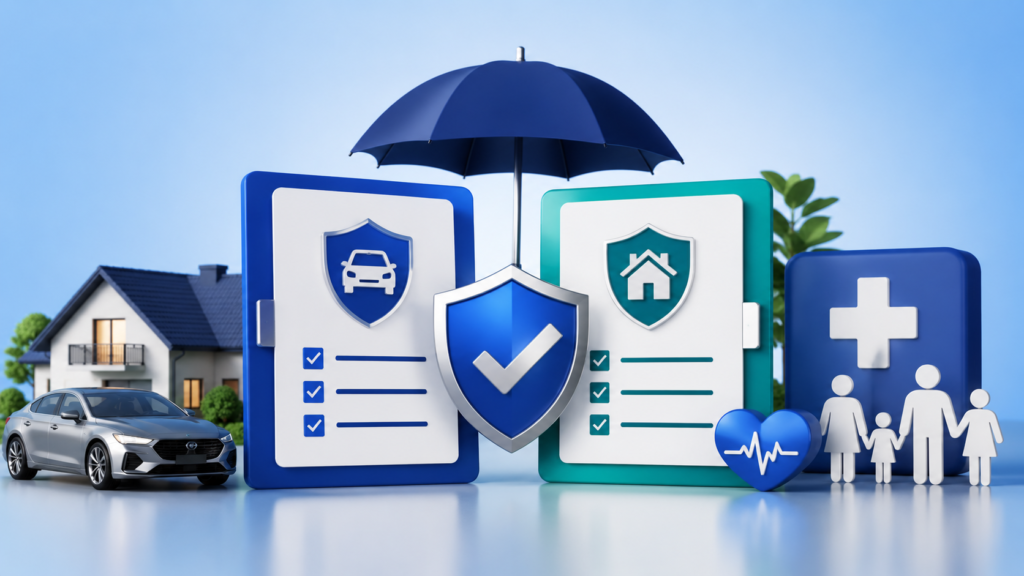
There are several reasons someone might have overlapping insurance coverage.
Sometimes it’s intentional. Other times, it’s simply a mistake.
Common examples include:
- Switching insurance companies without properly canceling the old policy
- Having coverage through two different sources
- Buying supplemental insurance
- Having an employer-sponsored insurance plan while also being covered under a spouse’s plan
- Carrying separate policies that provide different types of protection
- Refinancing or purchasing a vehicle while insurance arrangements change
- Forgetting that an existing policy is still active
The important thing is to understand whether the policies actually cover the same risk.
Two policies may appear similar but have different coverage limits, exclusions, deductibles, or purposes.
Two Health Insurance Policies
Having two health insurance plans is possible.
For example, a person may have health coverage through their own employer and also be covered under a spouse’s employer-sponsored plan.
In this situation, the plans generally don’t simply pay the same medical bill twice.
Instead, coordination of benefits is used to determine which plan pays first and which plan may pay after the primary plan.
The primary insurer generally processes the claim first. The secondary plan may then consider some remaining eligible expenses according to its own terms.
However, secondary coverage does not necessarily mean every remaining dollar will be paid.
Each policy has its own deductible, copayments, coinsurance, exclusions, and coverage limits.
That’s why having two health plans doesn’t automatically mean you’ll have zero out-of-pocket costs.
Can You Have Two Life Insurance Policies?
Yes.
Life insurance is different from property insurance because the benefit is generally based on the policy’s stated death benefit rather than reimbursement for a specific repair bill.
Someone might have multiple life insurance policies for different purposes.
For example, a person could have:
- Employer-provided life insurance
- An individual term life policy
- A separate policy purchased years earlier
- Coverage designed to help replace income
- A smaller policy intended for final expenses
If each policy is active and the insured meets the applicable conditions, beneficiaries may potentially receive benefits from multiple policies.
This is one area where having more than one policy can make sense.
The key is making sure the total amount of coverage fits the person’s actual financial needs and that the premiums remain affordable.
Two Auto Insurance Policies on the Same Car
Having two separate auto insurance policies on the same vehicle can create complications.
You generally shouldn’t purchase duplicate coverage simply because you think it will result in two payouts after an accident.
Auto insurance policies can contain other-insurance provisions explaining how coverage works when another policy may also apply.
There can also be differences between liability coverage, collision coverage, comprehensive coverage, uninsured or underinsured motorist coverage, and other protections.
If you discover that the same vehicle is insured by two companies, contact both insurers and explain the situation.
Don’t wait until an accident occurs to figure out which policy is supposed to respond.
Two Homeowners Insurance Policies
It’s also possible to have overlapping homeowners insurance policies, particularly when someone changes insurers and forgets to cancel an old policy.
But duplicate homeowners insurance doesn’t normally mean you can collect twice for the same covered property damage.
For example, imagine a covered loss causes $30,000 in damage.
If two policies apply, the insurers may determine how the loss should be handled according to their respective policy provisions and applicable law.
The amount you ultimately receive generally isn’t supposed to exceed the covered financial loss simply because multiple policies exist.
This is another reason to review your insurance after switching companies.
What Is Double Insurance?
Double insurance generally refers to a situation where the same risk is covered by more than one insurance policy.
For example, imagine you insure the same property with two insurers for the same type of loss.
Both policies may potentially respond to the same claim, but the policyholders generally aren’t entitled to profit from the loss.
Insurance contracts often contain provisions addressing situations where another policy also provides coverage.
These provisions can be complicated, and different policies may approach overlapping coverage differently.
If you’re dealing with a real claim, it’s important to read the actual policy documents rather than relying on a general assumption.
Can Two Insurance Companies Pay the Same Claim?
They can potentially both contribute to a covered claim, depending on the type of insurance and the applicable policy terms.
But that doesn’t necessarily mean you receive twice the value of your loss.
For example, suppose you have two policies that potentially cover a $10,000 loss.
The insurers may determine how much each company is responsible for based on their contracts and applicable rules.
The final amount paid to you may still be limited by the actual covered loss, policy limits, deductibles, and other applicable provisions.
This is why having two policies isn’t necessarily the same thing as having twice as much usable coverage.
Is It Worth Having Two Insurance Policies?
Sometimes yes, but it depends entirely on why you have them.
Having two policies can make sense when they serve different purposes.
For example, someone might intentionally maintain multiple life insurance policies because each one addresses a different financial need.
Similarly, two health plans can sometimes provide useful secondary coverage.
On the other hand, paying two premiums for essentially identical auto or homeowners coverage may simply waste money.
Before keeping two policies, ask yourself:
What does the second policy provide that the first policy doesn’t?
If the answer is “nothing,” you may be paying for unnecessary duplicate coverage.
Check Your Policy Before Canceling Anything
If you discover that you have two policies, don’t immediately cancel one.
First, compare the policies carefully.
Look at:
- Coverage limits
- Deductibles
- Premiums
- Exclusions
- Additional coverage
- Claim requirements
- Effective dates
- Cancellation terms
- Renewal conditions
A policy that appears more expensive might provide significantly better protection.
Similarly, the cheaper policy might have a higher deductible or important exclusions.
If you’re unsure, contact the insurer or a licensed insurance professional and ask them to explain the differences.
What If You Accidentally Bought Two Policies?
Mistakes happen.
You may have switched insurance companies but forgotten to cancel your old policy. Or you may have purchased a new policy before realizing that existing coverage was still active.
The best approach is to deal with the issue as soon as you notice it.
Check the effective dates of both policies and contact the insurers.
Ask whether one policy can be canceled and whether you’re entitled to any applicable refund under the policy’s cancellation terms and state requirements.
Keep written records of your conversations and confirmation of any cancellation.
Most importantly, make sure you don’t accidentally create a gap in coverage.
Don’t Hide One Policy From Another Insurer
If you have overlapping insurance, be transparent when filing a claim.
Tell the insurer that another policy may also provide coverage.
Trying to leave out relevant information can create unnecessary problems during the claims process.
Insurance companies have procedures for handling situations where multiple policies may apply.
It’s better to provide accurate information and allow the insurers to determine how the policies coordinate.
When Having Multiple Policies Makes Sense
There are situations where having multiple policies is perfectly reasonable.
For example:
Life insurance: Multiple policies can help address different financial goals.
Health insurance: A person may have primary and secondary coverage through different sources.
Supplemental insurance: A supplemental policy may provide benefits that aren’t included in a primary policy.
Different risks: Two policies may cover different aspects of the same general area of risk.
The key is understanding exactly what each policy does.
Multiple policies can provide broader protection when they are intentionally structured that way.
When Duplicate Insurance May Be a Waste of Money
Duplicate coverage becomes less useful when both policies essentially provide the same protection and you receive little additional benefit.
For example, paying two full premiums for identical homeowners coverage may not make financial sense if the second policy doesn’t meaningfully improve your protection.
Instead of automatically buying another policy, compare your existing coverage first.
You may be able to increase the limits or add a specific endorsement to your existing policy for less money and less complexity.
Yes, you can have two insurance policies covering the same person, property, or risk. But two policies don’t automatically mean two payouts.
Whether having multiple policies is useful depends on the type of insurance and what each policy actually covers.
With health insurance, two plans may coordinate benefits. With life insurance, multiple policies can potentially provide separate benefits. With property and auto insurance, overlapping policies generally involve rules that determine how insurers share responsibility for a covered loss.
If you discover that you have duplicate coverage, don’t panic and don’t immediately cancel one policy.
Compare the coverage, check the policy terms, understand the deductibles and limits, and contact the insurers if you’re unsure how the policies interact.
The goal of insurance isn’t to collect as many policies as possible. It’s to have the right protection for your actual financial risks without paying unnecessarily for coverage you don’t need.